Pledged but Unmeasured: What ESG Budget Data Reveals About Corporate Climate Accountability
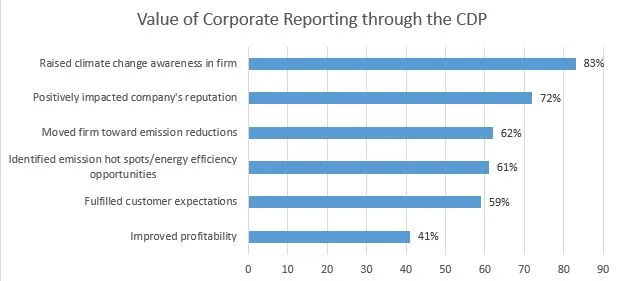
Photo: Rammck, CC BY-SA 4.0, via Wikimedia Commons
American corporations collectively allocated an estimated $35 billion toward environmental, social, and governance initiatives in 2023, according to aggregated corporate disclosure data reviewed by AP Ipsos Results. That figure represents a meaningful increase from prior years, and it has been accompanied by a surge in public commitments — net-zero pledges, carbon neutrality timelines, and ambitious scope-reduction targets announced at earnings calls and shareholder meetings alike. What the headline numbers rarely show, however, is the proportion of that spending that produces verifiable, third-party-confirmed environmental outcomes versus the portion directed toward communications infrastructure, reporting frameworks, and stakeholder engagement activities that generate visibility without necessarily generating change.
The distinction matters enormously. For investors, procurement teams, and policy analysts who depend on ESG disclosures to evaluate corporate behavior, the difference between a climate investment and a climate narrative is not merely semantic. It is the difference between a company that is reducing its carbon footprint and one that is reducing its carbon story.
Where the Money Actually Goes
A review of corporate sustainability reports filed by S&P 500 companies over a three-year period reveals a consistent pattern: the largest line items within ESG budgets tend to cluster around reporting, compliance infrastructure, and stakeholder communications. Capital expenditures directly tied to emissions reduction — renewable energy procurement, facility retrofits, supply chain decarbonization — represent a smaller share of total ESG spending than public announcements typically imply.
This is not simply a matter of accounting classification. Survey data collected from sustainability officers at mid-to-large US firms indicates that internal ESG teams frequently operate under dual mandates: demonstrate progress to external stakeholders and manage regulatory risk. When these two objectives compete for limited budget, the reputational mandate often prevails. One widely cited reason is timeline pressure. Operational changes to energy infrastructure or manufacturing processes take years to produce measurable results, while a refreshed sustainability report or a sponsored conference appearance delivers near-immediate stakeholder feedback.
The result is a portfolio of ESG expenditures that looks comprehensive on a slide deck but proves difficult to reconcile against actual emissions trajectories when independent analysts attempt the exercise.
The Measurement Problem at the Core
Perhaps the most revealing finding from cross-industry spending analysis is the inconsistency in how outcomes are defined and tracked. Unlike financial reporting, which operates within a standardized regulatory framework enforced by the SEC, ESG measurement remains largely voluntary and methodologically fragmented. Companies routinely select metrics that reflect favorably on their progress, adjust baseline years when targets prove difficult to meet, and apply varying scopes to emissions calculations in ways that make year-over-year comparison unreliable.
Consumer survey data adds another dimension to this problem. When American adults are asked whether they trust corporate sustainability claims, a majority express skepticism — yet the same respondents report that a company's stated environmental commitments influence their purchasing decisions. This creates a perverse incentive structure: companies face reputational rewards for making ambitious claims and limited reputational consequences when those claims go unverified, because the consumers who distrust the claims still respond to their presence.
For market researchers and ESG analysts, this dynamic is worth examining carefully. It suggests that the market signal driving ESG investment is not primarily a signal about environmental performance. It is a signal about perceived environmental seriousness — a softer, more malleable quality that can be manufactured through communications spending without requiring equivalent operational investment.
Third-Party Verification: The Gap Between Endorsement and Audit
A growing number of corporations now include third-party verification statements in their sustainability reports, a practice often cited as evidence of accountability rigor. However, an analysis of the verification landscape reveals significant variation in what these endorsements actually confirm. Many third-party reviews assess the accuracy of reported data rather than the adequacy of the underlying methodology or the ambition of stated targets. A company can receive a clean verification opinion on a sustainability report that accurately discloses minimal progress.
True independent auditing — the kind that evaluates whether a company's operational changes are consistent with its stated climate trajectory — remains rare and expensive. Among Fortune 500 firms, fewer than a third commission this level of scrutiny, according to data from sustainability assurance providers. The remainder rely on lighter-touch reviews that satisfy the optics of verification without providing the substantive accountability that sophisticated stakeholders increasingly demand.
This gap between endorsement and audit is precisely where the accountability theater dynamic is most visible. A verification logo on the cover of a sustainability report functions as a trust signal in stakeholder communications regardless of the depth of the underlying process. For companies operating in competitive industries where ESG ratings influence institutional investment flows, that signal has real economic value — and it can be obtained at a fraction of the cost of genuine operational transformation.
What Behavioral Data Suggests About Internal Prioritization
Beyond the numbers in public filings, behavioral signals from within corporate organizations offer additional insight. Internal survey data from workforce research indicates that sustainability-focused employees — those hired specifically to advance ESG objectives — report higher rates of role ambiguity and lower rates of cross-departmental influence than their counterparts in finance or operations. This structural marginalization limits the degree to which ESG commitments can penetrate the operational decision-making processes where genuine environmental impact is determined.
When capital allocation decisions are made, sustainability considerations are frequently treated as a constraint to be managed rather than a criterion to be optimized. Procurement data from manufacturing sectors shows that supplier selection processes nominally include ESG scoring, but price and delivery reliability consistently outweigh environmental performance metrics when final contracts are awarded. The scoring framework exists; the weighting structure undermines it.
Implications for Stakeholders Who Use ESG Data
For businesses that consume corporate ESG disclosures as inputs to investment, partnership, or procurement decisions, the patterns described above carry practical implications. Treating ESG budget size as a proxy for environmental commitment introduces systematic error into the analysis. A more reliable approach focuses on the ratio of capital expenditures tied to operational change versus expenditures directed toward reporting and communications, the specificity and enforceability of stated targets, and the presence of genuine third-party audit rather than lighter verification.
Survey-based methods also retain value here. Direct polling of sustainability officers, operations managers, and supply chain leads within target organizations can surface the internal prioritization dynamics that public disclosures are not designed to reveal. When behavioral data and stated commitments diverge, that divergence is itself a finding — one that carries significant implications for how corporate climate narratives should be weighted in strategic decision-making.
The sustainability scorecard, in other words, is only as useful as the rigor applied to grading it. Without that rigor, it remains a document of intentions — carefully formatted, professionally verified, and operationally optional.